Call Now • Free Consultation(954) 871-0041
Call
For homeowners & businesses

Property Insurance Claims and Disputes

In Florida, the winds, rain, storms and hurricanes are inevitable, unpredictable and carry devastating consequences to your home or business.

Types of loss

Claims we handle

Homeowner looking at a house with a wind-damaged roof

Wind Damage

High-velocity winds can cause property damage from blown off roofs and fences.
Couple sitting in a water-damaged living room

Water Damage

Florida insurance policies may cover water-related perils, such as burst pipes, but exclude other water damage types like flooding or sewage backup.
Homeowner sitting in front of a house hit by a fallen tree after a hurricane

Hurricane Damage

Hurricanes are devastating natural disasters that can cause severe and extensive damage to your business or home.
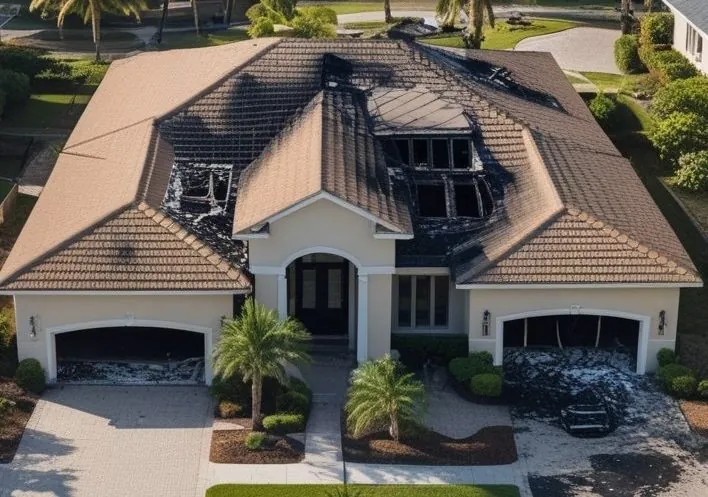
Aerial view of a home with a fire-damaged roof

Fire or Smoke Damage

Fire and smoke can have everlasting effects on the structure of a business or home and can cause significant damage to irreplaceable personal property.

The claim process

What happens after your property is damaged

The recommended steps in handling an insurance claim after your property sustains damage include the following:

  1. Step 1 of 6

    Document the Damage

    During and after the loss, document all damage with photographs and videos throughout the claim process.

  2. Step 2 of 6

    Report the Claim

    Promptly contact your insurer with a brief description of the damage and the date of the loss. Policies have specific timeframes within which the insurance company must be put on notice of the loss.

  3. Step 3 of 6

    Claim Investigation

    Your insurance company will ask questions about the loss and may request additional documentation, such as photographs, repair estimates and signed Proof of Loss documents.

  4. Step 4 of 6

    Property Inspection

    Your insurance company will send out an independent adjuster to your property to inspect the cause of the loss and the scope of damage to the property.

  5. Step 5 of 6

    Coverage Decision

    Your insurer will either:

    • deny your claim based on an exclusion under your insurance policy; or
    • acknowledge coverage of your loss but undervalue and underpay your claim.
  6. Step 6 of 6

    Seek Legal Representation

    An attorney may have to file a lawsuit to recover the full amount of compensation to restore your property to its pre-loss condition.

Contingency fee

No Fee Unless We Win

The Law Office of Matthew N. Grosswald operates on a contingency fee basis for property insurance litigation, which means we do not get paid unless we win your case. Additionally, most costs pre-settlement will be advanced by the firm to ensure you have the strongest case possible. If there is no recovery, you owe no attorney's fees and no costs.

Each client matter is handled with professionalism, personalized care and tenacious persistence.